 Hi Boox Popular Magazine 2025
California has some of the most specific car insurance requirements and market dynamics in the country, and understanding them before you shop produces better decisions than discovering the details after you have already purchased a policy.
From the mandatory minimum coverage requirements through the factors that affect premiums in the California market specifically, the landscape here is different enough from other states to be worth understanding on its own terms.
California’s Minimum Insurance Requirements
California law requires all drivers to carry a minimum level of liability insurance, and the requirements were updated effective January 1, 2025, with the first significant increase in decades.
The new minimums are $30,000 per person and $60,000 per accident for bodily injury liability, and $15,000 for property damage liability.
These minimums represent the floor of legal compliance, not a recommended coverage level. In a state with some of the highest vehicle repair costs, medical costs, and legal judgment levels in the country, the minimum limits are frequently inadequate to cover the actual costs of a serious at-fault accident.
A single vehicle collision in California can produce property damage well above $15,000. A multi-vehicle accident with injuries can produce bodily injury claims that exceed $60,000 per accident many times over.
Carrying liability limits significantly above the state minimum is the appropriate approach for any driver who wants to avoid personal financial exposure from judgments that exceed the coverage limit. The incremental premium cost of higher limits is modest relative to the protection they provide.
Uninsured Motorist Coverage in California
California has a significant uninsured motorist problem. Studies have consistently found that a meaningful percentage of California drivers operate without the legally required insurance, and many more carry only the minimum limits that are inadequate to cover serious injuries.
Uninsured motorist coverage and underinsured motorist coverage protect you when the driver who causes an accident cannot pay for your losses.
In California, insurers are required to offer uninsured motorist coverage, and drivers who decline it must do so in writing.
This coverage is worth carrying at meaningful limits rather than waiving to reduce the premium, particularly given the documented prevalence of underinsured and uninsured drivers on California roads.
The out-of-pocket cost of recovering from a serious accident caused by an uninsured driver without this coverage is a significant financial risk that the coverage addresses directly.
What Makes California Premiums Higher
California consistently ranks among the states with the highest average auto insurance premiums, and understanding why helps calibrate expectations when shopping. Several factors specific to the California market drive premium levels above the national average.
Traffic density and accident frequency in the major metropolitan areas, including Los Angeles, San Francisco, San Diego, and the surrounding regions, produce higher claim frequencies than lower-density markets.
Vehicle repair costs in California are among the highest in the country, driven by high labor rates and the prevalence of newer vehicles with expensive sensors, cameras, and driver assistance systems that increase the cost of even minor repairs significantly.
California also has a significant legal environment for auto accident claims, with active plaintiff’s bars and jury verdicts that are among the highest in the country.
The liability claim severity that insurers experience in California reflects this environment and is priced into premiums across the market.
Natural catastrophe exposure, including wildfire risk in many parts of the state, affects comprehensive coverage pricing in affected areas. And the state’s regulatory environment, which limits the factors insurers can use to price premiums and requires prior approval for rate changes, creates a market dynamic that affects how quickly premiums respond to claims trends.
The California Proposition 103 Factor
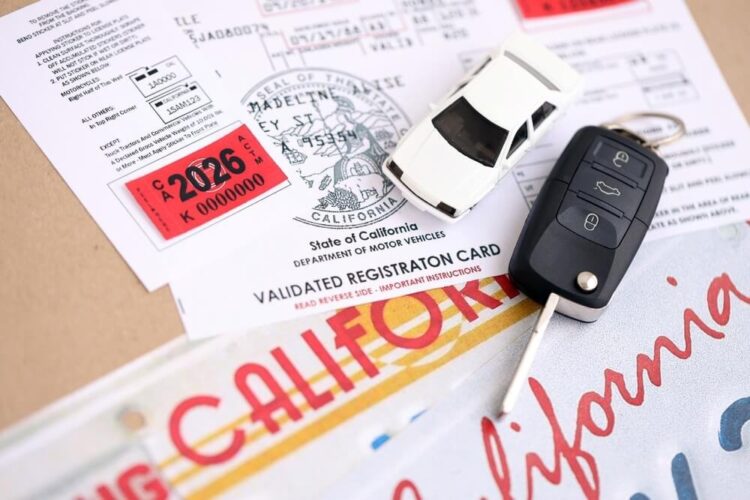
California’s Proposition 103, passed in 1988, requires that auto insurance rates be approved by the California Department of Insurance before taking effect and limits some of the rating factors that insurers in other states can use. Credit score, for example, cannot be used as a rating factor in California the way it can in most other states.
The factors that California insurers can use include driving history, the number of miles driven annually, and driving experience.
This regulatory environment means that the pricing dynamics in California differ from what drivers moving from other states may be accustomed to, and that the relative premium between different driver profiles reflects California-specific rules rather than national insurance pricing practices.
Shopping for California Car Insurance
W Insurance’s California car insurance service provides quotes across multiple carriers that operate in the California market, allowing comparison on consistent coverage terms that account for California’s specific requirements and market conditions.
The California market includes national carriers alongside regional and specialty insurers whose competitive positioning varies by driver profile, vehicle type, and geographic location within the state.
Shopping across multiple carriers rather than renewing with the current insurer or accepting the first quote received consistently produces better outcomes in California’s competitive but complex insurance market.
The carrier that is most competitive for an urban Los Angeles driver with a new vehicle is often not the same as the most competitive carrier for a rural Northern California driver with an older truck.
Coverage Considerations Beyond the Minimum
Beyond liability coverage, California drivers with financed or leased vehicles are required by their lenders to carry comprehensive and collision coverage. For owned vehicles, the collision and comprehensive decision is a financial calculation that should account for the vehicle’s current market value, the selected deductible, and the out-of-pocket cost of a total loss without coverage.
Medical payments coverage, which pays for medical expenses regardless of fault in an accident, is worth considering for drivers without strong health insurance coverage.
Gap insurance, which covers the difference between the vehicle’s market value and the outstanding loan balance in the event of a total loss, is worth considering for drivers who financed their vehicle with a small down payment and whose loan balance may exceed the vehicle’s depreciated market value.